Wednesday, May 09, 2007

Don’t pay for your calls...

... but rest assured you will pay for SMS, video, mCommerce, et al! VAS is the new emerging segment

It’s tough to charge you premiums for making calls nowadays with the cutthroat battle for market shares in the Indian telecom sector. As a logical follow through, companies are looking for attractive avenues to improve their ARPUS, and it is here that mobile VAS services come to the rescue. According to a recent report by the Internet & Mobile Association of India (IAMAI), the VAS industry in India is estimated at Rs.28.5 billion and is expected to grow by 60% to touch Rs.45.6 billion by the end of 2007.

It’s the right time to exploit all emerging opportunities in the mobile communications space. Sanjiv Mittal, CEO, Bharti Telesoft (VAS division of Bharti Enterprises Group), elucidates, “Th e main opportunity is the vast amount of content that can be delivered via mobile. The key is to collect that broad range of content and ensure it can be packaged and delivered in a meaningful & appealing way to individual subscribers and subscriber segments.”

Telecom companies, marketers, content providers and aggregators alike have realized this and are trying to reach out to conquer this relatively new terrain, but the road is tough. Anupam Mittal, CMD of People Group – Mauj Telecom, observes that as his company reaches the next level, “operational excellence, disruptive innovation and an unflinching focus on discovering customer needs is what we (Mauj Telecom) will need to distinguish ourselves.”

Entertainment hogs the limelight in the VAS space with P2P applications & ringtones attracting 75% of revenues. There are new, promising areas like mCommerce, which are yet to gain momentum. The low level of awareness, coupled with apprehensions of conducting transactions on mobile are the key reasons for the sluggish growth. The other prominent challenge that faces the industry at the moment is the revenue sharing mechanism in the industry between aggregator, copyright owner & operator. In fact, the discrepancy in revenue sharing is deterring lots of VCs from investing. With operators retaining the biggest chunk of revenues, the proposition of investing in content companies from the point of view of investors, becomes less & less lucrative.


This is a real concern, according to Rajiv Hiranandani of Mobile2win, one of the biggest players in the segment. “A lot of investments and resources go into creating and developing regional content. This can only be covered if telecom carriers give us a higher revenue share,” he said. Resolving issues like this, quickly, will benefit the sector.

With rapid mobile penetration, the VAS industry in India is standing at the vanguard of ocean of opportunities. Domestic and international remittances, cash-in and cash-out services and many other financial services on mobiles can become highly profitable stars in the near future, since there’s a rising need for speedy transactions. VAS will be the key differentiator for players in this competitive environment, as they will be able to profitably tap various customer segments for their services. As they say, companies always know how to make their customers ‘pay’!

Tuesday, October 10, 2006

THE BLASTOFF

THE BLASTOFF: Those who believed that the industry is moving towards the executive & premium segment, and that the economy segment is losing its shine, need to necessarily shift to euro 10 norms, pretty fast! Kalpesh Parekh, AVP, Equity Research, rejoins, “Companies can’t afford to neglect the economy segment. They need to have a dual model strategy. They should work on the economy segment for rural India and executive, premium segment bikes for the urban India.” Furthermore, in this rolling fiscal, Indian two wheeler space, especially the urban markets, will be driven by a technology revolution. Not counting the new bike launches, which occur faster than how ‘KK’ serials change on Rupert Murdoch’s cable channels. Evidently, two-wheeler gods & kings will be battling for the technological edge, even in the new launches. Hero Honda has already launched a fuel-injection model with 125-cc Glamour F1. The technology will be a brand new experience for Indian consumers. Closely on the heels of Hero Honda, Bajaj too is gearing up to launch the 200 (plus)-cc Pulsar armed with the world beater DTS-Fi (digital twin spark-fuel injection) technology (as opposed to the DTSi). Being successful with these truly innovative products will be the real test of mettle for both the emperors. Indian bikes for sure were due for a major electronic and technical overhaul, more than just mere cosmetic makeovers. But the biggest worry for both these companies would be, are Indian consumers getting so rich that they might just skip buying bikes (and shift to, say the Tata Rs.1 lakh car)? Well, all we know is that the scooter industry’s already dead... Long live

Friday, October 06, 2006

Christening your next new handset

Numbering game’s passé; it’s time for the ‘naming’ game, and then some more!

What’s in a name? Everything! Ask cellular handset makers in India, and the answer’s bound to be just that! And not without reason. The eye-popping success of the Moto RAZR series in India that is pulling up the sagging fortunes of the American handset-maker in the country, is a case in point. Lloyd Mathias, Director (Marketing), Motorola (India) believes that: “People do not understand confusing numbers and fundamentally, names arouse more response from target audiences.” The rave response to Motorola’s Moto RAZR, Moto PEBL, Moto SLVR, and the more recent, Moto ROKR series is reportedly also inspiring other handset makers to abandon their penchant with boring numbers and alphabets to name their snazzy models.

Till date, Nokia with a 79% share of the Indian market had in real terms exploited the Indian cellular handset freaks that could not resist its 3310, 3315, 1100, 2300, 6610, 6600, 7610 and other numbing numbered series. But perhaps today, think-tanks at the Finnish major are asking a question to themselves – can we fight competition better if we ‘name’ our handsets, instead of using plain vanilla digits for classifying the handsets? The answer is obvious by their announcement of naming their brands hereon.

Says Keith Pardy, Marketing Head (Global), Nokia, “What you will see coming from us in the future is not just a numbering system, you are going to start seeing names that carry a meaning and are important to consumers.” Call it piggy-backing on the innovative branding moves of their competitors or simply being copy-cats, the company has certainly realized that customers all around the world identify themselves with and respond well to product names that carry some connotation.

So have they already given shape to this plan with the Nokia 8800 Sirocco Edition launched recently? Or maybe they now believe that numbering their handsets make them unique, and hence have settled for a judicious mix of a name and a number to begin with! And come to think of it, there is an emotional connect when it comes to names and it’s more fun. There also comes a sense of ownership and style declaration with names. Digitally advanced all right, but ‘names’ unquestionably make the whole affair more palatable.

But then, why have strange sounding four-letter names... SLVR instead of Silver, RAZR instead of Razor and ROKR and COCKR in places of God knows what! “Consumers don’t look at these names in an abstract manner and therefore our four letter names are worked out accordingly to convey a message to consumers,” explains Mathias. Seems those guys out there did get the message. Or else why would Moto rave about its resounding success? Or why would other handset-makers latch on to the bandwagon? Why indeed!

Wednesday, October 04, 2006

We’re choking on the emissions!

The sunny state of California isn’t feeling particularly kind these days. The state has announced that it is going to sue six US and Japanese automakers (it’s a first of its kind legal battle in the US). And why? Because these six were contributing to global warming, that’s why. The offending parties are: Chrysler Motors Corporation (an arm of the Germany-based DaimlerChrysler); General Motors Corporation; Ford Motor Company; and the North American subsidiaries of Japanese carmakers Honda Motor, Nissan Motor and Toyota Motor.

These companies, charged the suit, are “among the world’s largest contributors to global warming and the adverse impacts on California.” The state’s Attorney General Bill Lockyer said that “global warming is causing significant harm to California’s environment, economy, agriculture and public health” and that the impacts are already costing the state millions of dollars and the price tag is increasing every passing day. If you jog your memory cells, you will remember that the state is led by Republican actor-turned-Governor ‘Terminator’ Arnold Schwarzenegger, who is at loggerheads with US President George W. Bush over environmental issues.

Saturday, September 23, 2006

China, India: Difference in the details

China and India are among the fastest growing economies in the world, with growth rates much admired by developing countries desperately struggling to crawl out of the poverty trap. Their abundance of relatively skilled labor at low cost has turned them into "factories of the world", and their huge populations in turn offer lucrative consumer markets for multinationals. These two Asian giants are tipped to become the world's next economic superpowers.

Nonetheless, a closer examination reveals that they offer competing models of development, though they became modern nations at about the same time, India in 1947, China in 1949. They launched reforms from different starting points: China embarked on market reforms in 1979 - a decade earlier than India - from a centrally planned, economically backward, agrarian economy; India initiated its reforms in the early 1990s and is today a semi-socialist economy in a fledging democracy ridden with problems of corruption and bureaucratic inefficiency. Today, China is seen to be ahead of India; but there is much speculation on their respective growth trajectories.

What do the numbers tell us?

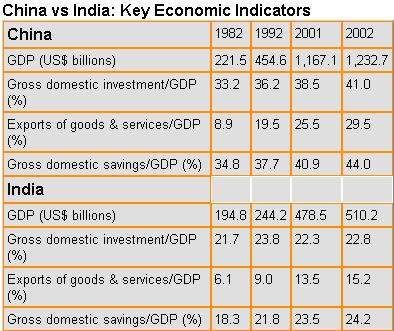
China's economic growth thus far is certainly more impressive than its South Asian cousin. China's gross domestic product (GDP) grew by an average of 9.7 percent during 1982-92, and by 9 percent during 1992-02. On the other hand, India grew by 5.6 percent and 6 percent in the same respective periods, though still impressive by most developing countries' standards. India's lagging is due to a number of reasons. The Chinese save twice as much as Indians: for every US$1 earned, the Chinese save 44 cents, compared with 24 cents by Indians. As a result, the Chinese invest more in their economy than do the Indians. The share of gross domestic investment in GDP is 41 percent in China, compared to 22.8 percent in India. The Chinese economy is also more opened to international trade, and therefore gains from greater specialization in areas where China excels. China's export share of GDP is twice that of India's.

A more compelling reason to account for India's slower growth is the flows of foreign direct investment (FDI). As shown in the diagram below, the amount of FDI into India is only a small fraction of that into China. Of course, any statistics, especially those reported by communist cadres who are rewarded for economic performance of their localities, should be taken with a grain of salt. As frequently pointed out, China's FDI figures are likely to be exaggerated by "round-tripping" - domestic capital disguised as foreign investment (passed through Hong Kong) to qualify for special investment incentives reserved for foreigners. India's FDI figures, however, may be understated because they exclude foreigners' reinvested profits, the proceeds of foreign stock market listings, intra-company loans, and so forth. This may not be a simple issue of whether India is able to attract foreign investment, since it may have as much to do with New Delhi's policy or practice for years of keep foreign investors out of the country.

Foreign vs private companies

China may boast impressive records in courting foreign investors, but it has few successful indigenous private companies on which it can pride itself. China's private companies are systematically discriminated against by the capital market and the legal system. Private property rights have only recently been recognized by the central government and given legal recognition and protection. The state-owned banking system is notorious for molly-coddling the inefficient and debt-laden state-owned enterprises, while shying away from the vibrant private sector.
The stock markets are also largely reserved for those enterprises with state backing. Ironically, foreign companies in China are granted better recognition, legal protection and market access than indigenous private companies. The internationally better known Chinese firms, such as China Telecom, and the white goods, or major appliance, maker Haier, were formerly nurtured in the state cradle. China Telecom is a state-owned enterprise, and Haier was formerly a collectively owned township and village enterprise (TVE).

In stark contrast, India's brand of internationally well-known companies, such as software giants Infosys Technologies and Wipro, and pharmaceutical and biotech start-ups Ranbaxy and Dr Reddy's Labs, are born and bred locally. "Indeed, by relying primarily on organic growth, India is making fuller use of its resources and has chosen a path that may well deliver more sustainable progress than China's FDI-driven approach," write Huang Yasheng and Tarun Khanna, dons from the Sloan School of Management at the Massachusetts Institute of Technology, MIT, and the Harvard Business School, in an article published in Foreign Policy in August, 2003.

"China's export-led manufacturing boom is largely a creation of foreign direct investment, which effectively serves as a substitute for domestic entrepreneurship," they argue.

The point about India's better use of resources is worth noting, as the numbers seem to lend support to this hypothesis. China's GDP growth rate (8 percent in 2002) is about double that of India (4.6 percent); however, China's savings ($542 billion) are four times higher than India's ($122 billion), not to mention that its FDI inflows are more than 10 times greater ($52 billion compared with $3.5 billion).

Not just markets - institutions matter

Why is entrepreneurship able to flourish in India but not in China? "Blossoming entrepreneurship in India is due in part to a liberalizing financial market, which provides capital access previously exclusive to certain caste groups to the budding entrepreneurs. Capital is now available to private start-ups, through venture capitalists, the banking system, and the stock markets," says Vijay Kelkar, an advisor to the Indian Ministry of Finance, at a speech recently delivered at the Australian National University in Canberra.

Aside from a financial market that allocates resources more efficiently, India seems to have in place the institutions - democracy, a functioning judiciary, property rights and so on - conducive to economic development. Huang and Khanna, from MIT and Harvard, argue: "Democracy, a tradition of entrepreneurship, and a decent legal system have given India the underpinnings necessary for free enterprise to flourish." Of the world's top 200 small-sized companies listed by Forbes in 2002, 13 were from India; while four were China's - all of them based in Hong Kong.

Nonetheless, China's greater openness to the outside world and its ability to benefit from foreign trade and investment can be attributable to a "stronger state" (albeit authoritarian), one that is able to advocate and implement policies in the country's interests, rather than being held hostage by any vested interest groups. By contrast, India's burgeoning but unruly democracy means that in order to gain power, the Indian policy makers are often trapped in myopic vested interests and are sometimes held hostage by protectionist voices.